What is the scope and industry significance of the Mixed Martial Arts Equipment Market?
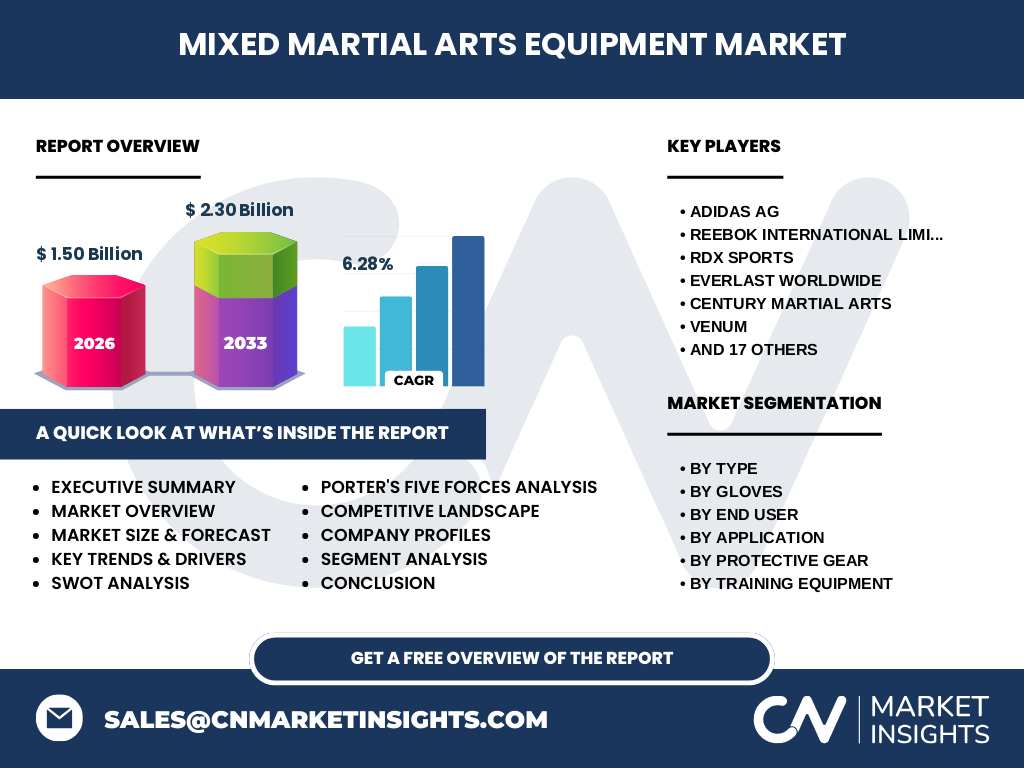
Our analysis indicates that the Mixed Martial Arts Equipment Market represents a vital manufacturing and retail sector encompassing specialized gear for combat sports athletes. Valued at $1.50 Billion in 2026, this industry governs the safety, performance, and regulatory compliance of fighters worldwide. The sector bridges raw material suppliers, such as premium leather and high-density foam manufacturers, with global distribution networks operating through major logistics hubs like the Port of Shanghai and the Port of Los Angeles.
Structural Growth Drivers and Restraints Shaping the Sector
The market is propelled by the surging popularity of professional promotions like the UFC and localized amateur circuits. Key growth drivers include rising disposable incomes and mainstream fitness integration, while strict safety standards enforced by bodies like the Association of Boxing Commissions act as structural restraints. Supply chain bottlenecks involving synthetic polymers and polyurethane foam present ongoing logistical hurdles for tier-one equipment fabricators.
Emerging Trends and Growth Patterns in the Industry
The data suggests a pronounced consumer shift toward IoT-enabled training tools and eco-friendly gear constructed from sustainable vegan leather substitutes. Brands are investing heavily in antimicrobial fabric treatments to combat bacterial degradation in sparring gloves and shared mats. This trajectory favors agile manufacturers capable of rapidly prototyping high-durability gear that meets stringent Association of Boxing Commissions safety mandates without sacrificing ergonomic mobility.
COVID-19 Impact Analysis and Post-Pandemic Recovery
Pandemic-era gym closures caused a temporary contraction in institutional equipment sales, yet this was counterbalanced by a massive surge in home-gym personal-use purchases. Brands specializing in heavy bags and grappling gloves experienced unprecedented direct-to-consumer demand. The recovery trajectory highlights a resilient supply chain restructuring, moving away from single-source manufacturing toward diversified fabrication hubs across Southeast Asia to mitigate future geopolitical and logistical disruptions.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features a mix of heritage brands and specialized combat sports innovators. Adidas AG and Everlast Worldwide leverage vast global distribution networks, whereas boutique specialists like Hayabusa Fightwear Inc. and Venum capture market share through advanced wrist-support technologies and proprietary synthetic leather innovations. Market concentration is moderately fragmented, forcing mid-tier players to invest aggressively in digital marketing and athlete sponsorships.
Executive Summary: High-Level Synthesis of Key Findings
Our research forecasts the Mixed Martial Arts Equipment Market to expand from $1.50 Billion in 2026 to $2.30 Billion by 2033, achieving a robust CAGR of 6.28%. Growth is anchored by increasing MMA gym participation and rigorous athletic commission regulations. Strategic consolidation and material science advancements remain the primary vectors for sustained profitability across sporting goods retailers and specialized online storefronts.
Projected Growth Trajectory: 2027 to 2033 Market Forecast
Driven by sustained consumer interest in combat sports conditioning, the market is projected to scale steadily through 2033. Our models indicate that cumulative investments in e-commerce infrastructure and lightweight composite materials will accelerate adoption across emerging economies. Stakeholders must prepare for capital expenditure cycles focused on automated manufacturing lines to meet the surging global demand for durable training equipment and protective gear.
Comprehensive Segmentation Analysis
The market is intricately segmented to address diverse consumer and institutional requirements:
• By Type: Gloves, Protective Gear, Training Equipment
• By Gloves: Sparring Gloves, Grappling Gloves, Bag Gloves, Competition Gloves
• By End User: Personal-Use, Institution
• By Application: Sporting Goods Retailers, Online Retailers
• By Protective Gear: Headgear, Mouthguards, Shin Guards, Groin Protectors
• By Training Equipment: Punching Bags, Focus Mitts and Pads, Mats, Heavy Bags
Geographic Distribution and Regional Performance
North America maintains the largest revenue share, sustained by high concentrations of professional training camps and robust consumer spending on fitness gear. Meanwhile, the Asia-Pacific region demonstrates the fastest growth rate, fueled by expanding disposable incomes, urban fitness center expansion, and the rising popularity of regional MMA promotions in countries like Japan, Thailand, and China.
In-Depth Regional Review of Key Markets
North American growth is underpinned by established retail partnerships with major sporting goods chains, whereas European markets face stricter chemical compliance regulations regarding synthetic leather treatments. In Asia-Pacific, localized production hubs in Thailand—capitalizing on traditional Muay Thai manufacturing expertise—supply high-quality leather shin guards and focus mitts to Western markets, establishing crucial trans-Pacific trade corridors.
Strategic Positioning of Leading Companies
Industry leaders maintain distinct competitive moats through product innovation and targeted athlete endorsements. Century Martial Arts dominates institutional supply contracts, while Fairtex and Twins Special leverage authentic, hand-crafted leather goods to capture purist consumer segments. Meanwhile, RDX Sports and Title Boxing LLC focus on aggressive digital-first direct-to-consumer strategies, optimizing online retail conversion funnels for gloves and protective gear.
Porter's Five Forces Analysis of Competitive Pressures
Rivalry within the sector is intense, driven by numerous equipment brands competing for shelf space in major sporting goods retail outlets. The threat of substitutes remains moderate, as alternative fitness regimes cannot replicate specialized combat training requirements. Supplier power is constrained by abundant raw material alternatives, whereas buyer power is high due to transparent online pricing and numerous competing product lines.
SWOT Analysis of the Mixed Martial Arts Equipment Market
Strengths: Established brand loyalty and continuous material science innovations.
Weaknesses: Vulnerability to raw material price volatility for premium leather.
Opportunities: Untapped expansion in emerging digital fitness ecosystems and female-focused gear lines.
Threats: Stringent international safety standards and counterfeit products eroding profit margins for authentic manufacturers like Venom and Hayabusa Fightwear Inc.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material extraction—procuring genuine leather, polyurethane, and high-density EVA foam. Mid-chain operations involve specialized molding, stitching, and structural testing conducted by manufacturers like Rival Boxing Gear Inc. and Combat Sports. The downstream phase routes products through international shipping ports to sporting goods retailers, online platforms, and institutional gyms before reaching individual practitioners.
Strategic Investment Insights and High-Potential Areas
Investors should target direct-to-consumer digital infrastructure and sustainable material innovators to capture outsized returns. Brands that successfully integrate smart sensors into striking pads and heavy bags command premium valuations. Furthermore, strategic joint ventures focusing on localized manufacturing in Latin America and Southeast Asia present compelling opportunities to mitigate long-haul maritime logistics risks.
Conclusion and Strategic Takeaways
The industry's expansion to $2.30 Billion by 2033 underscores the enduring commercial viability of combat sports. Success in this evolving landscape requires a dual focus on rigorous product safety compliance and agile e-commerce fulfillment. Companies embracing advanced materials and direct consumer engagement will outpace legacy competitors bound to traditional retail models.
Research Methodology and Data Triangulation
Our baseline estimates are derived through rigorous data triangulation, combining customs trade registry databases, primary stakeholder interviews with executive leadership from Tatami Fightwear and Everlast Worldwide, and secondary macroeconomic indicators. Quantitative regression models cross-reference historical retail sales with gym membership growth metrics to ensure forecast accuracy across all geographic regions.
Scope of the Report and Coverage Parameters
This comprehensive analysis evaluates global market dynamics for MMA equipment spanning historical baselines through the 2027 to 2033 forecast period. Limitations include potential underreporting of decentralized, unbranded local manufacturing units in developing regions. The scope explicitly isolates professional and consumer-grade combat equipment, excluding generalized fitness apparel and non-contact athletic accessories.
Recent Industry Developments and Strategic Moves
Recent market activity is characterized by aggressive product line expansions and high-profile promotional sponsorships. Brands like Adidas AG and Reebok International Limited have restructured their combat sports divisions to prioritize lightweight, moisture-wicking protective gear. Simultaneously, strategic partnerships between equipment manufacturers and digital streaming platforms highlight an industry-wide pivot toward integrated digital-physical fitness ecosystems.